

The past 12 months have drawn a sharp line between two business models. Software-as-a-Service stocks are in freefall, while marketplace businesses have held their ground, with most categories outperforming SaaS by 15 to 45 percentage points. Here is what the data shows, and why the divergence is more than a trade rotation.
The Headline Numbers
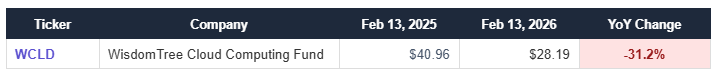
From February 13, 2025 to February 13, 2026, the divergence between SaaS and marketplace stocks has been stark. The WisdomTree Cloud Computing fund (WCLD) is one of the purer emerging SaaS ETFs, and is down -31.2% over the 12 month period. Comparatively, marketplaces outside of labor marketplaces have held their ground.
While we see the appeal of labor marketplaces, they tend to be less defensible over time, which is why they are outside SNAK’s core investment thesis. Factors such as multi-tenanting, and low switching costs mean these platforms struggle to build durable network effects. Unlike marketplaces with tightly integrated communities or highly specialized supply, labor marketplaces face continual churn and competitive pressure, making long-term defensibility a challenge.

Put another way: if you held an equal-weighted basket of every marketplace name in our analysis excluding labor, versus a WCLD SaaS ETF, your marketplace portfolio would have outperformed by more than 30 percentage points over the last 12 months.
Part I: The SaaS Selloff
The SaaS selloff of early 2026 is not a routine correction. It reflects a genuine re-rating of the business model — one that has been building since late 2025 and accelerated sharply in the first weeks of this year.
WisdomTree Cloud Computing Fund (WCLD): −31.2%
The ETF has shed over 30% of its value in 12 months. The culprit is fear: specifically, rapid advances in generative AI have sparked investor concern that traditional SaaS and cloud firms may face disrupted business models or compressed pricing power. While WCLD contains a lot of emerging SaaS companies, more mature SaaS stocks have also seen a fall from grace, Adobe and Salesforce are both down 42.5% over this same period.
Part II: Why Marketplaces Are Holding Up
The relative resilience of marketplace stocks is not accidental. It reflects structural differences in how marketplace businesses create value — differences that make them less vulnerable to the specific fears driving the SaaS selloff.
The Core Distinction
SaaS companies primarily sell software: code that automates or enhances a business process. If AI can perform that same function without a software license, the SaaS company loses. Marketplace companies, by contrast, facilitate transactions between buyers and sellers. Their value is not the software itself — it is the liquidity, the trust infrastructure, the network effects, and in many cases the physical logistics that make the transaction possible. AI does not disintermediate a two-sided network the way it disintermediates a software tool.
eBay connects 130+ million buyers with sellers globally — AI does not replace that network.
Airbnb’s value is the vetting, the reviews, the payments, and the trust layer around a home rental — not the booking software.
Carvana reconditions, finances, and delivers physical vehicles. Logistics and physical assets cannot be AIed away.
DoorDash coordinates real-time delivery logistics across hundreds of thousands of gig workers. That coordination network has real-world moats.
Asset & Real World Marketplaces: Mixed to Positive Performers
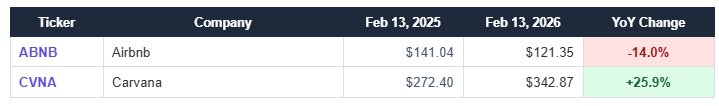
Airbnb and Carvana — the two “asset marketplace” names in our basket — are the one of two categories averaging positive 12 month returns, up +6% on average. Carvana is the standout, up 25.9% from a year ago, driven by strong anticipation of its Q4 2025 earnings report (expected February 18) and continued market share gains in used vehicle retail. Airbnb is down 14%. The stock has been punished primarily for decelerating growth and margin compression from investments in new business lines, despite still-strong underlying fundamentals like strong free cash flow and double-digit revenue growth.
Horizontal Marketplaces: Neutral to Positive
The horizontal marketplace category — eBay, Alibaba Group, and MercadoLibre — is up an average +15%, with eBay and Alibaba Group in positive territory at +18.9% and +30.3% respectively. This is a remarkable contrast to SaaS: eBay, often written off as a mature, slow-growth business, has outperformed high-profile SaaS names like Adobe and Salesforce by more than 60 percentage points in the last year (both Adobe and Salesforce are down -42.5% over the same period).
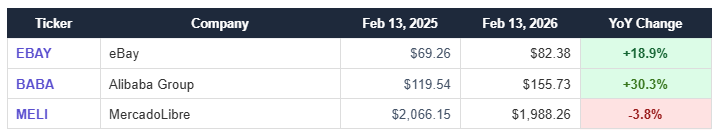
Mobility & On-Demand: Mixed but Still Beating SaaS
The on-demand category is divided, but even here the average (−15.9%) handily beats WCLD’s SaaS average of −31.2%.
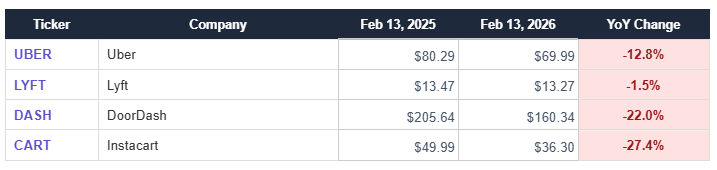
Labor Marketplaces: The Exception to the Rule
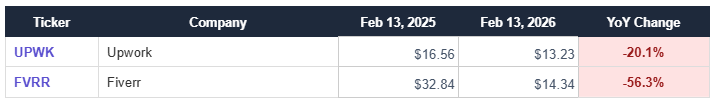
The labor marketplace category — Upwork and Fiverr — is a meaningful outlier in the marketplace outperformance story, with both names down sharply. Upwork is off 20.1% and Fiverr 56.3%. These companies sit at an awkward intersection: they are marketplaces by structure, but their product — human knowledge work — is precisely what AI is most directly threatening. The market is treating them more like SaaS than like Airbnb or eBay, and for understandable reasons. The question for both is whether AI expands the total addressable market for freelance work or destroys it.
Part III: The Narrative Behind the Numbers
Why This Is Not Just a “Risk-Off” Rotation
It would be tempting to explain this divergence as simple risk-off behavior — investors selling high-multiple tech and rotating to value. But that does not fully explain it. eBay currently trades at roughly 4x revenue, up from a 5-year average of 3x. Adobe is at roughly 5x, a sharp decline from its 5-year average of 12x. If this were purely multiple compression, both should be falling. The fact that eBay is up while Adobe is down suggests something more specific is at work.
The specific fear is AI disruption of the SaaS revenue model. Enterprise software companies charge recurring subscription fees for access to software that helps people do their jobs. If AI agents can do those jobs directly — or if foundation models make bespoke software irrelevant — the subscription fee disappears. Marketplaces, with their network effects and transaction-based revenue, are structurally harder to disrupt in this way.
The Three Categories of Risk
When you look across the names in our analysis, the performance pattern maps onto three distinct AI risk profiles:
High AI disruption risk (worst performers): Adobe, Salesforce, IGV, Fiverr — all businesses where the core product is software-driven knowledge work that AI directly threatens.
Moderate AI risk (middle of the pack): AirBnB, Uber, Lyft, MercadoLibre, DoorDash, Instacart — businesses with real-world components that add friction to AI disruption, but still carry some exposure.
Low AI disruption risk (best performers): Carvana, eBay, Alibaba — businesses where the value is the network, the physical asset, or the logistics, not the software itself.
Note: This post is for informational purposes only and should not be considered investment advice. Please do your own research.
Thank you to Adam Koopersmith for editing and sharpening this piece.
Excellent post Sonia. Is this just a B2C play or also affecting B2B Saas and MKP models?